Closing Costs 101: What Palm Beach Buyers Really Pay
Most buyers budget carefully for their down payment and then get blindsided at the closing table by a second bill they didn't plan for. In Palm Beach County, that second bill — closing costs — typically runs 2% to 5% of your purchase price, on top of whatever you're putting down. On a $500,000 home, that's a swing of $10,000 to $25,000 in cash you need to have ready before you get the keys.
Here's the part most buyers never hear from their agent: that number isn't fixed, and a meaningful chunk of it can be offset before you ever open your wallet.
10-Second Deal-Math Puzzle 🧮
Quick math before we dive in:
You're buying a $500,000 home. Your total closing costs land at $15,000 (the realistic midpoint of the 2–5% range). With Palm Beach Homes' 1% buyer cashback rebate, you get $5,000 back at closing.
Question: What percentage of your closing costs does that rebate offset?
Answer: $5,000 ÷ $15,000 = 33%. One-third of your closing costs, covered — just for working with an agent who structures the deal differently.
What's Actually Inside "Closing Costs"?
"Closing costs" isn't one fee — it's a bundle of separate charges from your lender, the title company, and the state of Florida. Here's what's typically in it:
Lender fees. Your loan origination fee usually runs around 1% of your loan amount. This covers the cost of underwriting and processing your mortgage.
Appraisal and inspection. Your lender will require an appraisal (roughly $400–$600) to confirm the home is worth what you're paying. A home inspection (roughly $300–$500) is optional but strongly recommended — skipping it to "win" a competitive offer can cost far more later.
Title insurance. Florida regulates title insurance rates by law, so premiums don't vary much between title companies — but you still need both an owner's policy (protects you) and a lender's policy (protects your mortgage company), which together typically run about 0.5%–0.6% of the purchase price.
Florida's documentary stamp tax. This is where Florida differs from a lot of other states. Florida charges a documentary stamp tax on the mortgage note — $0.35 per $100 borrowed (0.35% of your loan amount) — plus an intangible tax of 0.2% on the loan amount. These are state-mandated and not negotiable.
Recording fees. A smaller, flat-ish cost (usually $100–$200) to officially record the deed and mortgage with Palm Beach County.
Prepaid escrows. This is the line item that surprises buyers most. Your lender will typically require you to prepay several months of property taxes and homeowners insurance into an escrow account at closing. In Palm Beach County, where windstorm and flood insurance premiums run higher than the national average, this can be a bigger number than people expect — sometimes several thousand dollars on its own.
HOA estoppel fee (if applicable). If you're buying into a community with an HOA or condo association, expect a $200–$400 fee to obtain your estoppel letter confirming the account is current.
The Numbers on a $500,000 Purchase
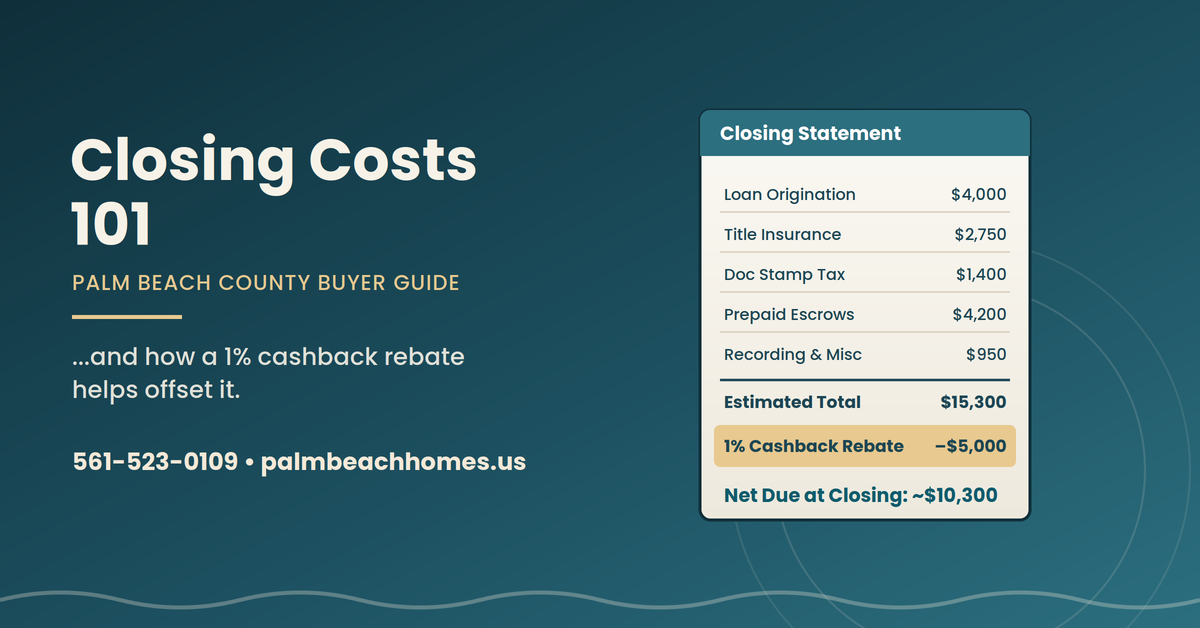
| Closing Cost Item | Typical Range | Approx. on $500,000 Purchase |
|---|---|---|
| Loan origination fee (~1% of loan, 80% LTV) | 0.8%–1% of price | ~$4,000 |
| Appraisal fee | Flat fee | ~$500 |
| Home inspection | Flat fee | ~$400 |
| Owner's + lender's title insurance | 0.5%–0.6% of price | ~$2,750 |
| Documentary stamp tax (mortgage note) | 0.35% of loan | ~$1,400 |
| Intangible tax (mortgage) | 0.2% of loan | ~$800 |
| Recording fees | Flat fee | ~$150 |
| Prepaid escrows (taxes + insurance) | Varies widely | ~$3,000–$5,000+ |
| Estimated Total | 2%–5% of price | ~$13,000–$18,000 |
| Palm Beach Homes 1% Buyer Cashback | 1% of price | –$5,000 |
| Your Net Out-of-Pocket Closing Costs | ~$8,000–$13,000 |
Figures are estimates for illustration based on 2026 Florida market data and a $500,000 purchase price at 80% loan-to-value. Your actual costs will vary by lender, loan type, insurance provider, and specific closing details.
The Palm Beach Homes Advantage
Most buyer's agents in Palm Beach County collect their commission and send you to the closing table to figure the rest out on your own. That's the standard model — and it's exactly what we do differently.
When you buy with Palm Beach Homes, you get full buyer representation — home tours, offer strategy, negotiation, and closing coordination from start to finish — plus a 1% cashback rebate of your purchase price paid directly to you at closing. On a $500,000 home, that's $5,000 you can apply toward your closing costs, use to buy down your rate, or simply keep as liquidity after move-in.
This rebate is disclosed upfront to everyone in the transaction, including your lender, and is subject to standard closing approval and underwriting requirements — there's no catch, and no reduction in the level of service you receive.
Key Takeaways
- Florida buyer closing costs typically run 2%–5% of your purchase price, separate from your down payment.
- Florida's documentary stamp tax and intangible tax on mortgages are state-specific costs most out-of-state buyers don't expect.
- Prepaid escrows for property taxes and insurance are often the single largest — and most underestimated — line item in Palm Beach County.
- A 1% cashback rebate can offset roughly a third of your total closing costs on a typical purchase.
- The rebate doesn't reduce your representation — you still get full-service buyer support from offer to close.
Ready to Run Your Own Numbers?
Every purchase is different, and the fastest way to know your real number is to run it yourself. Use the savings calculator at palmbeachhomes.us to see exactly what your 1% cashback rebate looks like on your target price, or call Imon Rashid directly at 561-523-0109 to talk through your specific closing cost estimate before you write an offer.
Palm Beach Homes is an authorized real estate team operating under the licensed brokerage Atlantic Florida Properties. The 1% buyer cashback rebate is disclosed in advance to all interested parties in the transaction, including the buyer's lender and the seller, and is subject to final closing approval and underwriting thresholds where applicable. Figures in this post are estimates for informational purposes only and do not constitute financial or legal advice — consult your lender and title company for exact figures specific to your transaction.